YOU BRING YOUR SUPERPOWERS
We'LL bring the mortgage strategy
The business you built. The portfolio you assembled. The income you earned on your own terms. That's your superpower. Our job is the strategy that makes the mortgage system understand it.
YOU BRING YOUR SUPERPOWERS
We'LL bring the mortgage strategy
The business you built. The portfolio you assembled. The income you earned on your own terms. That's the superpower. Our job is the strategy that makes the mortgage system understand it.
YOU BRING YOUR SUPERPOWERS
We'LL bring the mortgage strategy
The business you built. The portfolio you assembled. The income you earned on your own terms. That's the superpower. Our job is the strategy that makes the mortgage system understand it.
What's Your Superpower?
SEVEN buttons. EIGHT powers. Choose your own adventure.
What's Your Superpower?
six buttons. Each one routes to a specific income situation.
What's Your Superpower?
six buttons. Each one routes to a specific income situation.
HERo Stories
Three borrowers. Three superpowers the system almost missed.
STORY 1
HER tax returns said $40k.
HER business said something very different
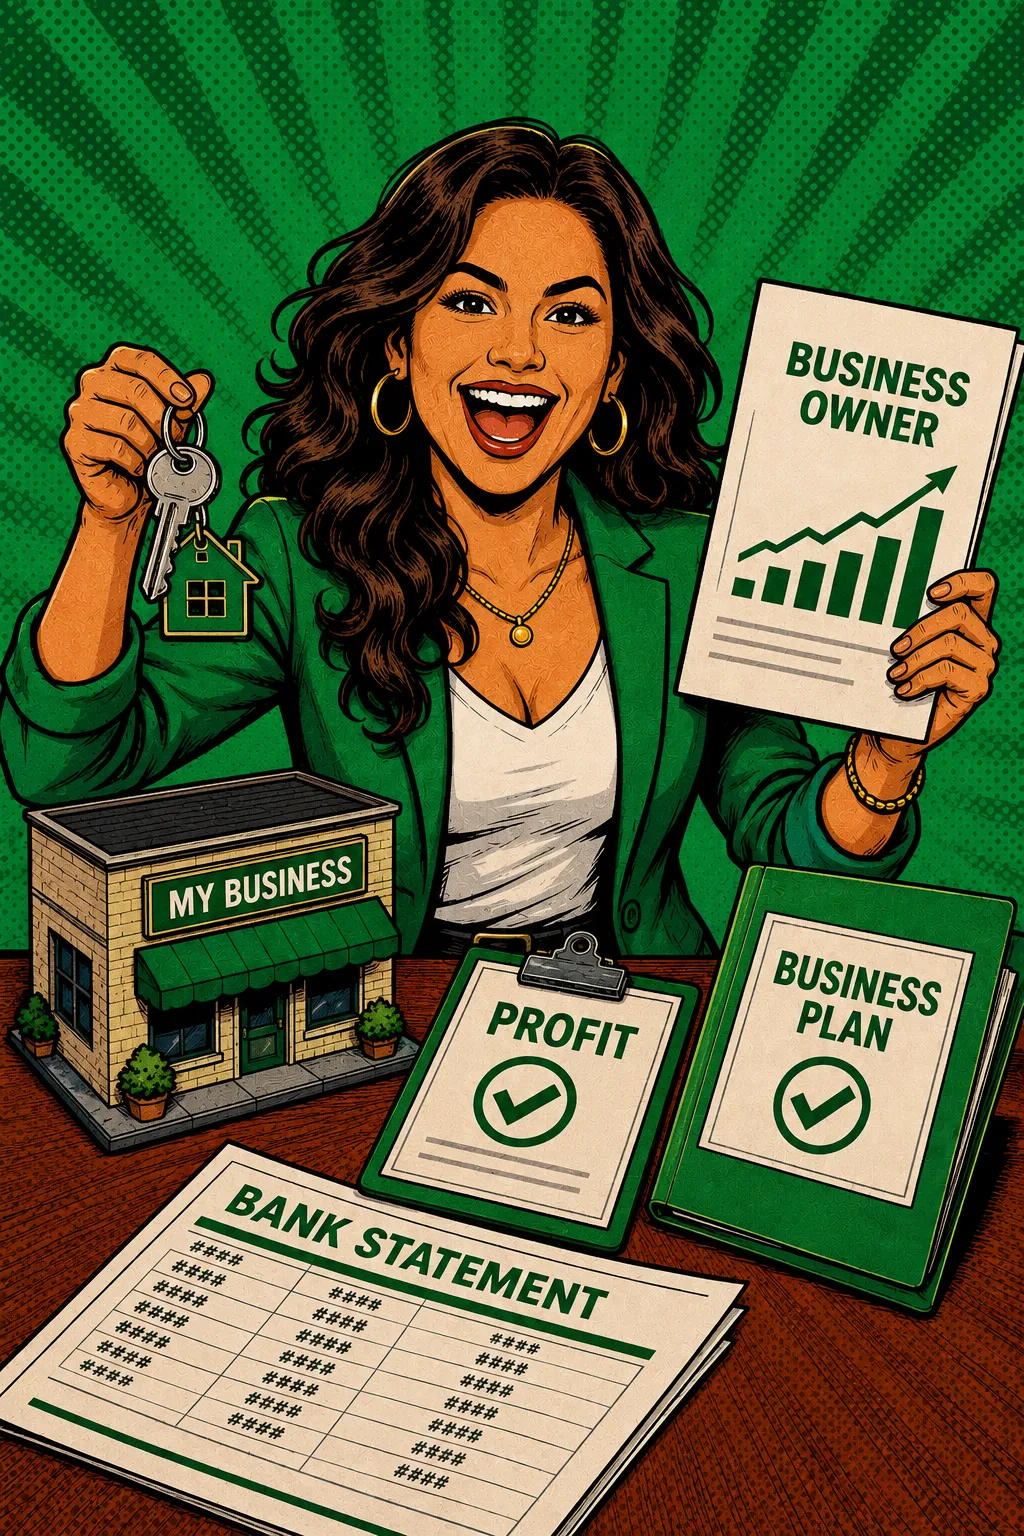
A successful business owner wanted to buy a $1.8 million home, but her tax returns didn’t come close to showing what her businesses actually produced.
Instead of trying to untangle years of tax returns across multiple companies, we used 12 months of business bank statements from her strongest business to document the income that was really there.
20% down. Qualified in under 24 hours. Closed in under 30 days.
Story 2
Nine reasons other lenders said no.
We only needed one reason to say yes.
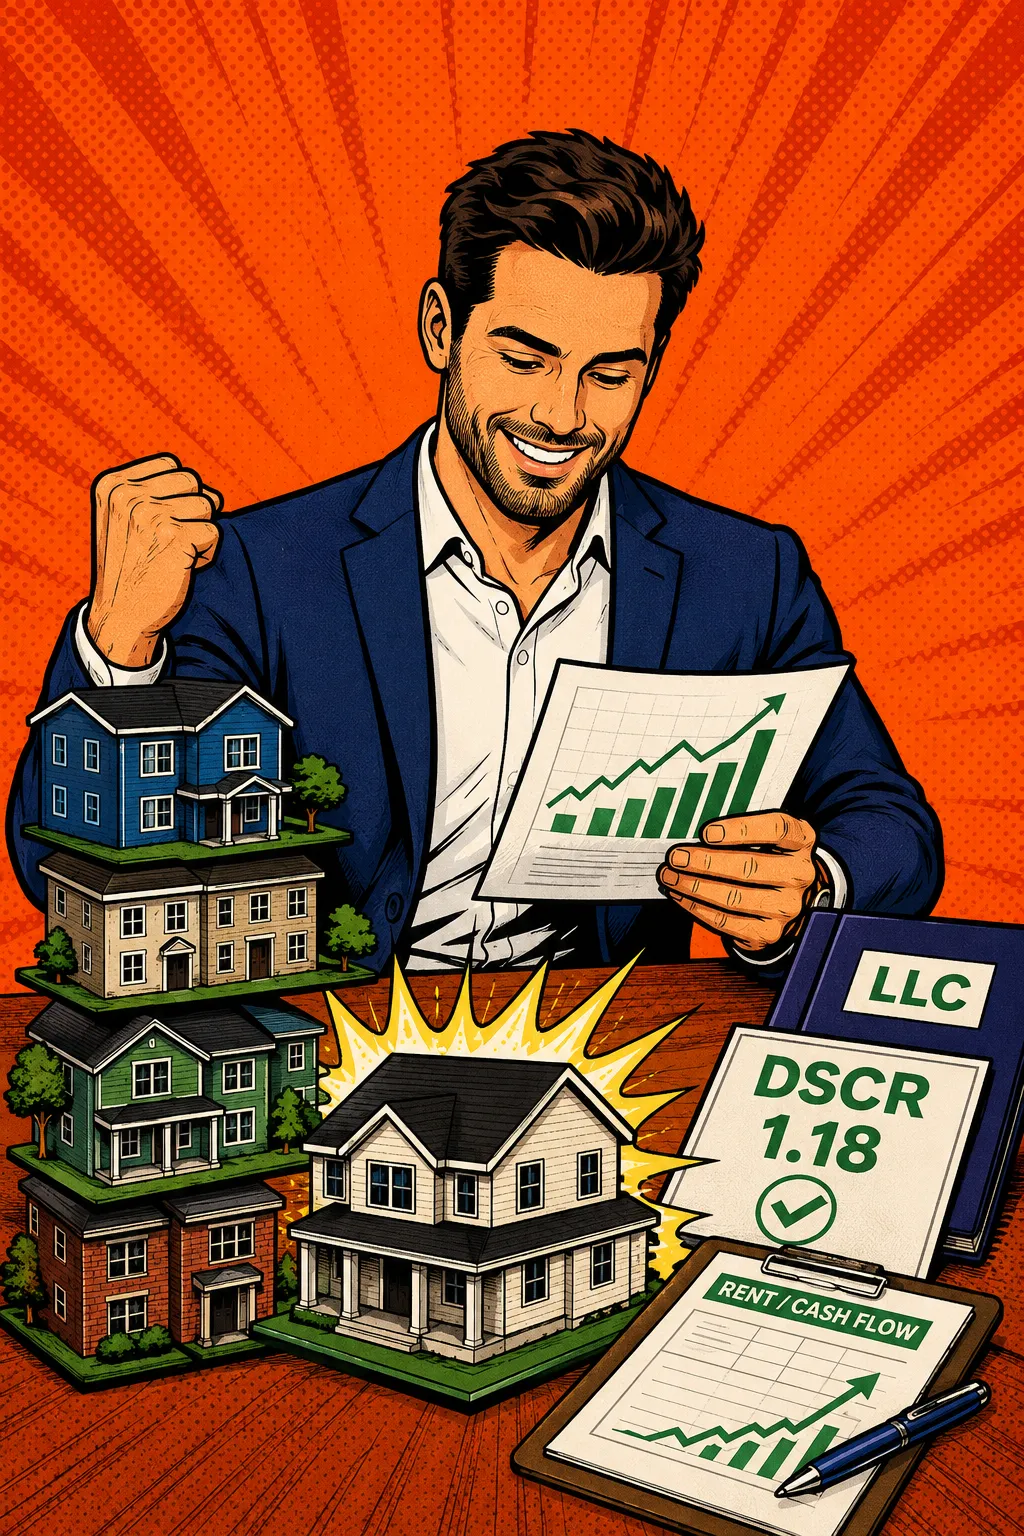
This real estate investor had a file traditional lenders hated: short-term rental income, a four-unit property, owned by a trust, a cash-out refinance, and non-permanent residency.
Several lenders said no.
We looked at what actually mattered: 12 months of real Airbnb income showing the property was already paying for itself. We found a program built for the deal instead of trying to force the deal into the wrong program.
The refinance closed, and the cash helped fund the investor’s next purchase.
Story 3
The Money was there.
The mortgage rules just didn't know what to do with it.
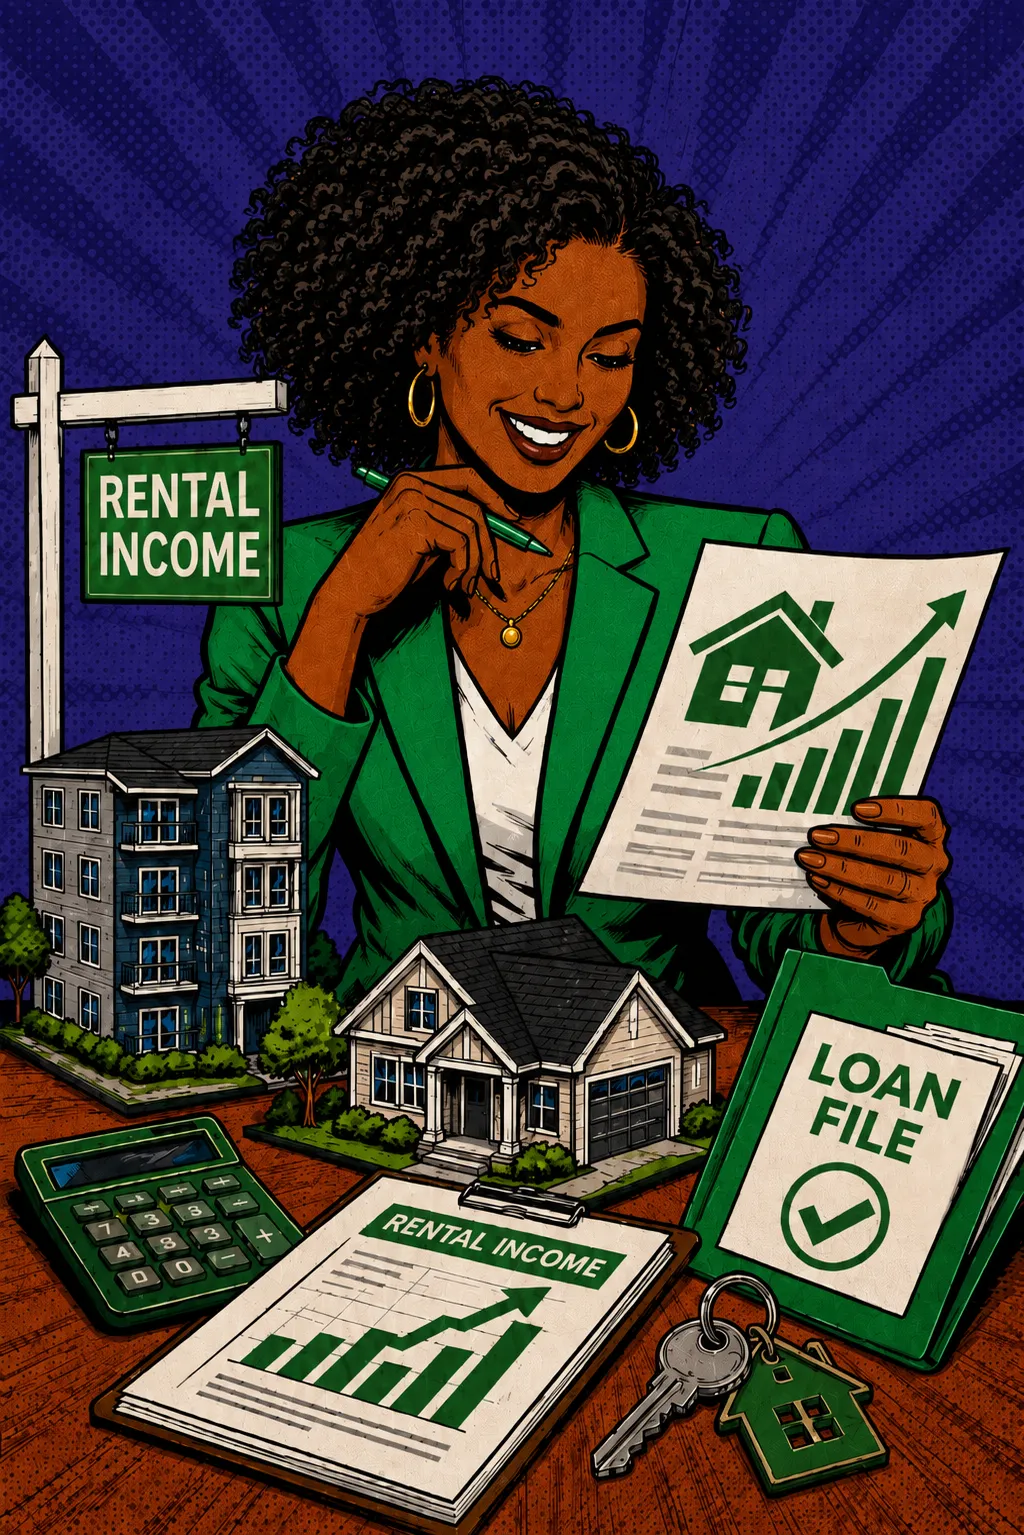
This entrepreneur buys businesses, grows them, sells them, then does it again. Great business model. Terrible fit for traditional mortgage underwriting.
Even a Bank Statement program wanted to exclude some of their largest deposits because they came from business sales.
So we changed the strategy.
Using a trailing 12-month Profit & Loss statement supported by recent bank statements, we documented the business the way it actually operated.
Multiple lenders had already said no. We got the cash-out mortgage done.
FAQ — questions worth asking before you assume no
My CPA writes everything off. Does that kill my mortgage options?
It doesn't have to. Your tax strategy might be working perfectly — which means the tax return is not the right document for your mortgage. The Bank Statement method reads your actual deposits instead of your tax returns. Send two months of business bank statements and we'll run both numbers side by side. No application. No credit pull.
I was already told no. Is that the end of the road?
A denial from one lender describes that lender's box. It does not always describe your options. Most of the time when a complicated file gets denied, it is because the lender used the wrong document to evaluate it. Send the denial reason and we'll tell you whether a different document, a different product, or a different sequence produces a different outcome.
Bank statement loans have higher rates. Is it worth it?
There is typically a rate premium — ask for current pricing when you're ready, because it moves with the market. The better question is whether the qualifying income advantage outweighs the rate difference on a real monthly payment. Our Bank Statement calculator shows you the actual numbers so you can decide.
Can I hold the investment property in my LLC?
DSCR investment loans can close in the name of your LLC from day one. Conventional, FHA, and VA loans require personal title. If entity ownership is part of the strategy, the investor section walks through which structure fits which product — and why getting the structure right from the start matters. Really, all primary residence loans require personal title or vesting in a trust.
My income varies a lot month to month. Does that disqualify me?
Variable income is one of the most common things the Beige Box misreads. The question is which 12 or 24-month window tells the most accurate story of what you actually earn. Some files work better with bank statements. Some with a certified P&L. Send the account history and we'll figure out which approach produces the number that reflects your real earnings.
HERo Stories
Three borrowers. Three superpowers the system almost missed.
STORY 1
HER tax returns said $40k.
HER business said something very different
A successful business owner wanted to buy a $1.8 million home, but her tax returns didn’t come close to showing what her businesses actually produced.
Instead of trying to untangle years of tax returns across multiple companies, we used 12 months of business bank statements from her strongest business to document the income that was really there.
20% down. Qualified in under 24 hours. Closed in under 30 days.
Story 2
Nine reasons other lenders said no.
We only needed one reason to say yes.
This real estate investor had a file traditional lenders hated: short-term rental income, a four-unit property, owned by a trust, a cash-out refinance, and non-permanent residency.
Several lenders said no.
We looked at what actually mattered: 12 months of real Airbnb income showing the property was already paying for itself. We found a program built for the deal instead of trying to force the deal into the wrong program.
The refinance closed, and the cash helped fund the investor’s next purchase.
Story 3
The Money was there.
The mortgage rules just didn't know what to do with it.
The Money Was There. The Mortgage Rules Just Didn’t Know What to Do With It.
This entrepreneur buys businesses, grows them, sells them, then does it again. Great business model. Terrible fit for traditional mortgage underwriting.
Even a bank statement program wanted to exclude some of their largest deposits because they came from business sales.
So we changed the strategy.
Using a trailing 12-month Profit & Loss statement supported by recent bank statements, we documented the business the way it actually operated.
Multiple lenders had already said no. We got the cash-out mortgage done.
FAQ — questions worth asking before you assume no
My CPA writes everything off. Does that kill my mortgage options?
It doesn't have to. Your tax strategy might be working perfectly — which means the tax return is not the right document for your mortgage. The Bank Statement method reads your actual deposits instead of your tax returns. Send two months of business bank statements and we'll run both numbers side by side. No application. No credit pull.
I was already told no. Is that the end of the road?
A denial from one lender describes that lender's box. It does not always describe your options. Most of the time when a complicated file gets denied, it is because the lender used the wrong document to evaluate it. Send the denial reason and we'll tell you whether a different document, a different product, or a different sequence produces a different outcome.
Bank statement loans have higher rates. Is it worth it?
There is typically a rate premium — ask for current pricing when you're ready, because it moves with the market. The better question is whether the qualifying income advantage outweighs the rate difference on a real monthly payment. Our Bank Statement calculator shows you the actual numbers so you can decide.
Can I hold the investment property in my LLC?
DSCR investment loans can close in the name of your LLC from day one. Conventional, FHA, and VA loans require personal title. If entity ownership is part of the strategy, the investor section walks through which structure fits which product — and why getting the structure right from the start matters. Really, all primary residence loans require personal title or vesting in a trust.
My income varies a lot month to month. Does that disqualify me?
Variable income is one of the most common things the Beige Box misreads. The question is which 12 or 24-month window tells the most accurate story of what you actually earn. Some files work better with bank statements. Some with a certified P&L. Send the account history and we'll figure out which approach produces the number that reflects your real earnings.
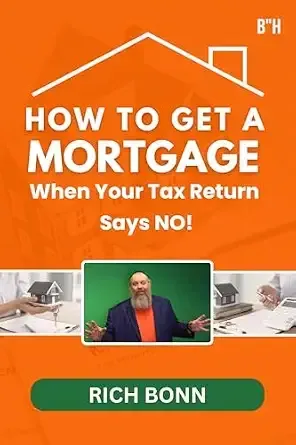
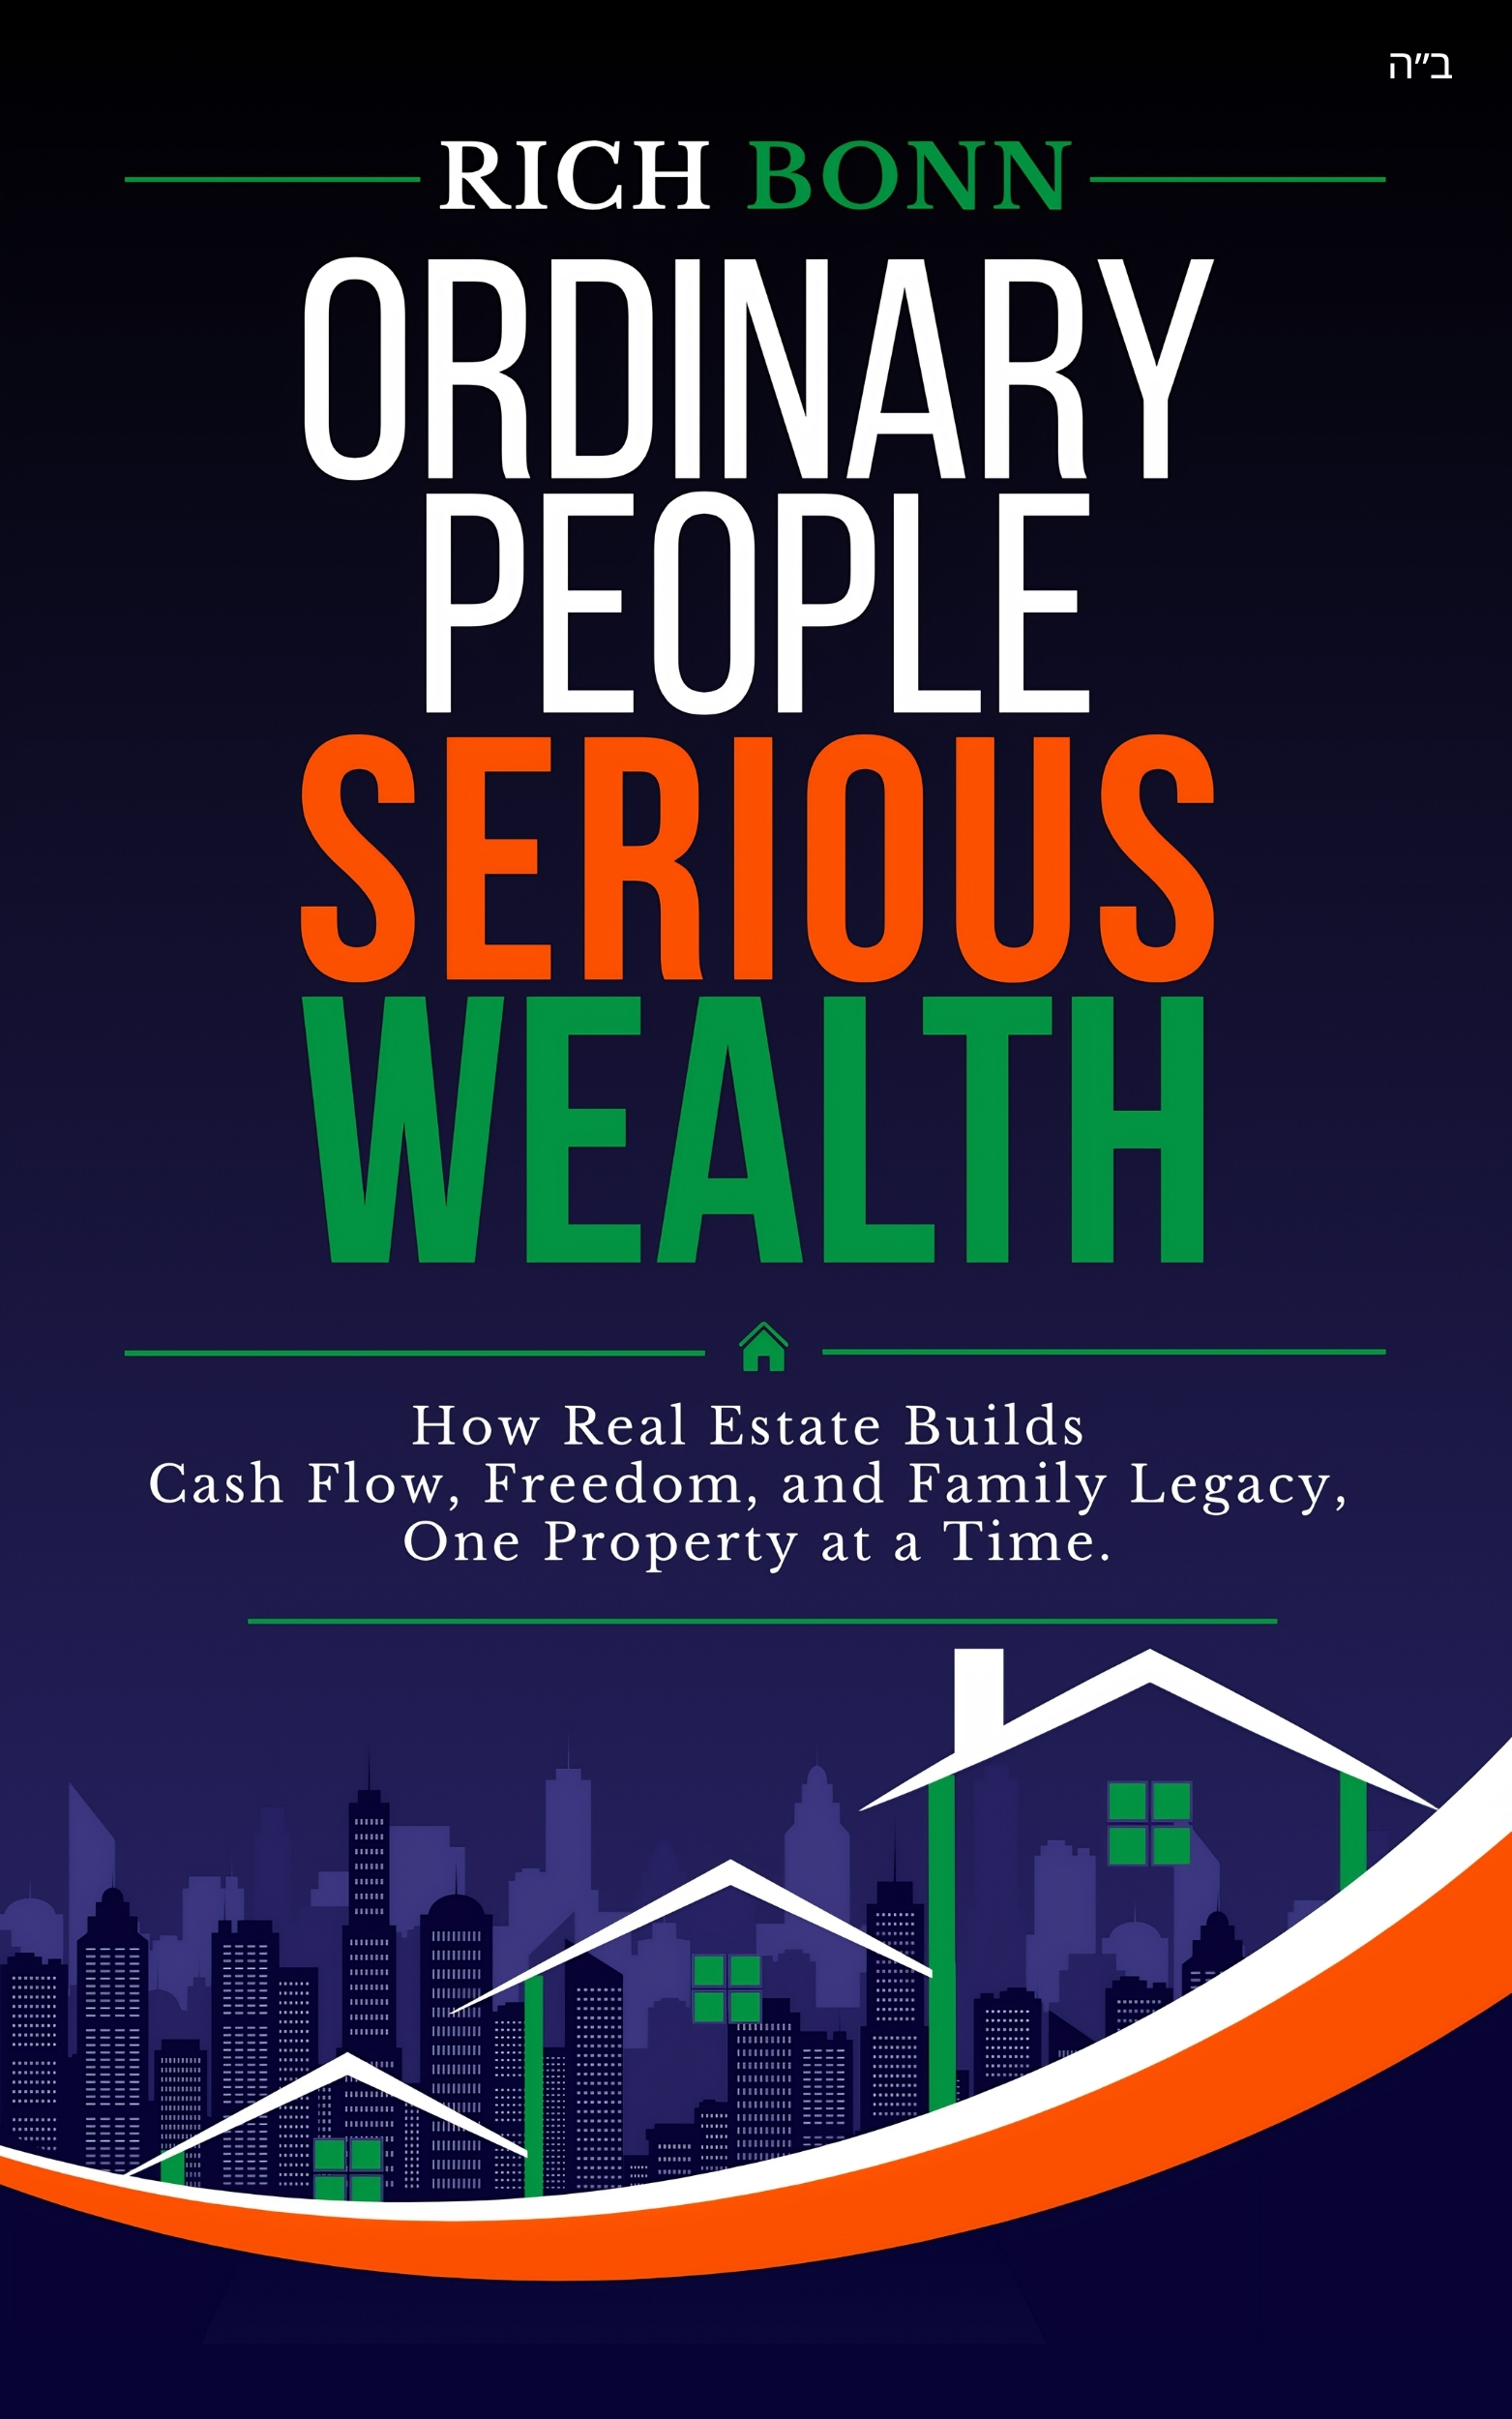
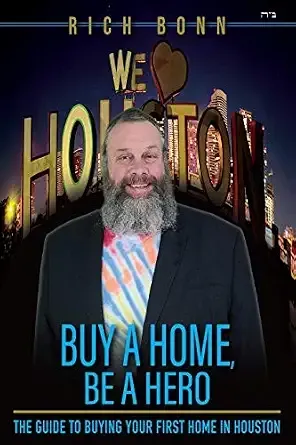
THREE BOOKS. THE COMPLETE MAP.
First-time buyers in Houston, self-employed borrowers the system got wrong, and investors building wealth that lasts past the first property.
THREE BOOKS. THE COMPLETE MAP-
First-time buyers in Houston, self-employed borrowers the system got wrong, and investors building wealth that lasts past the first property.
Don't take our word for it
THREE BOOKS. THE COMPLETE MAP.
First-time buyers in Houston, self-employed borrowers the system got wrong, and investors building wealth that lasts past the first property.
Complicated? Simple? We welcome all Income types.
No matter how complicated — we WORK just as hard.
Not every mortgage needs a complicated strategy.
At Habayit Home Loans, we build the right strategy around you.
No pressure. No beige-box nonsense. Just a clear path forward.
Let’s look at your options and figure out what makes sense.
Don't take our word for it
Don't take our word for it
Check out our latest blogs...
Check out our latest blogs...
Check out our latest blogs...
Contact Us
Rich Bonn, NMLS #278696
Branch Manager
(281) 841-1723
4660 Beechnut Street, Suite #225, Houston, TX 77096
Site Accessibility Assistance
Habayit Home Loans is committed to ensuring our website is accessible to all users, including individuals with disabilities. If you experience any difficulty accessing content or wish to request an accommodation, please CONTACT US HERE. When reaching out, include the web page URL and a description of the issue you encountered.
CONSUMERS WISHING TO FILE A COMPLAINT AGAINST A MORTGAGE BANKER OR A LICENSED MORTGAGE BANKER RESIDENTIAL MORTGAGE LOAN ORIGINATOR SHOULD COMPLETE AND SEND A COMPLAINT FORM TO THE TEXAS DEPARTMENT OF SAVINGS AND MORTGAGE LENDING, 2601 NORTH LAMAR, SUITE 201, AUSTIN, TEXAS 78705. COMPLAINT FORMS AND INSTRUCTIONS MAY BE OBTAINED FROM THE DEPARTMENT’S WEBSITE AT WWW.SML.TEXAS.GOV. A TOLL-FREE CONSUMER HOTLINE IS AVAILABLE AT 1-877-276-5550. THE DEPARTMENT MAINTAINS A RECOVERY FUND TO MAKE PAYMENTS OF CERTAIN ACTUAL OUT OF POCKET DAMAGES SUSTAINED BY BORROWERS CAUSED BY ACTS OF LICENSED MORTGAGE BANKER RESIDENTIAL MORTGAGE LOAN ORIGINATORS. A WRITTEN APPLICATION FOR REIMBURSEMENT FROM THE RECOVERY FUND MUST BE FILED WITH AND INVESTIGATED BY THE DEPARTMENT PRIOR TO THE PAYMENT OF A CLAIM. FOR MORE INFORMATION ABOUT THE RECOVERY FUND, PLEASE CONSULT THE DEPARTMENT’S WEB SITE AT WWW.SML.TEXAS.GOV.
By submitting any forms on this page or website and providing your mobile number, you are opting in and consent to receive text messages at the number provided, including messages that may be marketing or promotional, or for customer support. Messages may be automated or sent by an autodialer. Message and data rates may apply. There is no purchase necessary, and message frequency varies. Reply STOP to cancel and HELP for help. You can view our Terms of Service and Privacy Policy at the links provided.
Contact Us
Rich Bonn, NMLS #278696
Branch Manager
(281) 841-1723
4660 Beechnut Street, Suite #225, Houston, TX 77096
Site Accessibility Assistance
Habayit Home Loans is committed to ensuring our website is accessible to all users, including individuals with disabilities. If you experience any difficulty accessing content or wish to request an accommodation, please CONTACT US HERE. When reaching out, include the web page URL and a description of the issue you encountered.
Copyright 2026. All rights reserved. Rich Bonn NMLS # 278696 | Habayit Home Loans a DBA of The Turnkey Foundation Inc Branch 2523747 | Company | 236669 Equal Housing Opportunity | Equal Housing Lender
Habayit Home Loans a DBA of The Turnkey Foundation Inc
Branch 2523747 | Company 236669
CONSUMERS WISHING TO FILE A COMPLAINT AGAINST A MORTGAGE BANKER OR A LICENSED MORTGAGE BANKER RESIDENTIAL MORTGAGE LOAN ORIGINATOR SHOULD COMPLETE AND SEND A COMPLAINT FORM TO THE TEXAS DEPARTMENT OF SAVINGS AND MORTGAGE LENDING, 2601 NORTH LAMAR, SUITE 201, AUSTIN, TEXAS 78705. COMPLAINT FORMS AND INSTRUCTIONS MAY BE OBTAINED FROM THE DEPARTMENT’S WEBSITE AT WWW.SML.TEXAS.GOV. A TOLL-FREE CONSUMER HOTLINE IS AVAILABLE AT 1-877-276-5550. THE DEPARTMENT MAINTAINS A RECOVERY FUND TO MAKE PAYMENTS OF CERTAIN ACTUAL OUT OF POCKET DAMAGES SUSTAINED BY BORROWERS CAUSED BY ACTS OF LICENSED MORTGAGE BANKER RESIDENTIAL MORTGAGE LOAN ORIGINATORS. A WRITTEN APPLICATION FOR REIMBURSEMENT FROM THE RECOVERY FUND MUST BE FILED WITH AND INVESTIGATED BY THE DEPARTMENT PRIOR TO THE PAYMENT OF A CLAIM. FOR MORE INFORMATION ABOUT THE RECOVERY FUND, PLEASE CONSULT THE DEPARTMENT’S WEB SITE AT WWW.SML.TEXAS.GOV.
By submitting any forms on this page or website and providing your mobile number, you are opting in and consent to receive text messages at the number provided, including messages that may be marketing or promotional, or for customer support. Messages may be automated or sent by an autodialer. Message and data rates may apply. There is no purchase necessary, and message frequency varies. Reply STOP to cancel and HELP for help. You can view our Terms of Service and Privacy Policy at the links provided.