1099 mortgage
what you built... and what the system misses
1099 Mortgage
what you built... and what the system misses
1099 Mortgage
what you built... and what the system misses
What your clients paid you.
Not what survived the tax returns.
Two years of 1099s. No tax return required. The difference between what you earned and what you reported may change everything.
"Your income is inconsistent." (No. It’s variable. Those are different things.)
"We need a single employer." (I have twelve clients. That’s better than one.)
"We need two years of returns showing this income." (They’re going to show every write-off too, and you’re going to use it against me.)
You’ve been made to feel like a question mark. You are, in fact, to the answer.
What Your Clients paid you.
Not what survived the tax returns.
Two years of 1099s. No tax return required. The difference between what you earned and what you reported may change everything.
"Your income is inconsistent." (No. It’s variable. Those are different things.)
"We need a single employer." (I have twelve clients. That’s better than one.)
"We need two years of returns showing this income." (They’re going to show every write-off too, and you’re going to use it against me.)
You’ve been made to feel like a question mark. You are, in fact, to the answer.
What your clients paid you.
Not what survived the tax returns.
Two years of 1099s. No tax return required. The difference between what you earned and what you reported may change everything.
"Your income is inconsistent." (No. It’s variable. Those are different things.)
"We need a single employer." (I have twelve clients. That’s better than one.)
"We need two years of returns showing this income." (They’re going to show every write-off too, and you’re going to use it against me.)
You’ve been made to feel like a question mark. You are, in fact, to the answer.
🦸
Your Superpower
You built a client base that pays you on your terms. Independence was the whole point. Every 1099 is a relationship you earned — proof of work, proof of competence, proof of a business someone chose to hire.
🌀
What the Beige Box gets wrong
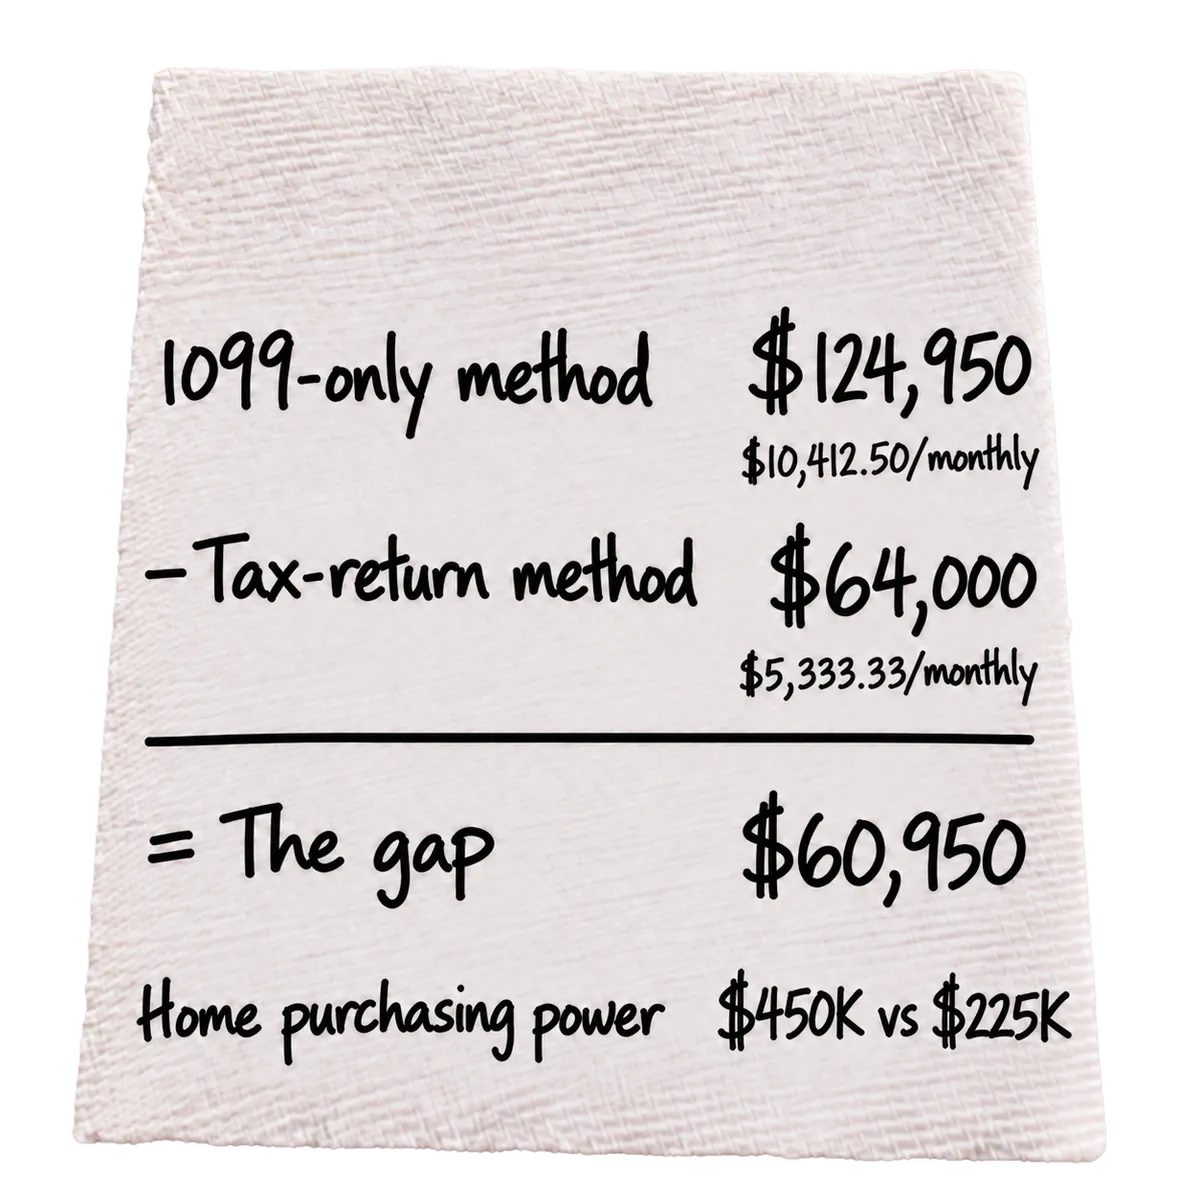
The Beige Box reads your earnings through the tax return, subtracts every legitimate write-off, and qualifies you on the taxable remainder. You earned $147,000. The 1099s prove it. The Beige Box removed every deduction your accountant was right to take and presented you with a qualifying income that looked nothing like what you actually made. It didn’t hate you. It just wasn’t designed for you.
💥
The Strategy - how it works
The 1099-only path bypasses the tax return entirely. It reads your gross 1099 income and applies a standard expense factor instead of your actual deductions. The result is a qualifying income that, for most 1099 earners, is materially higher than the tax return shows.
What the Lender will look at
1.
One to two years of all 1099 forms from all sources.
2.
Two months of bank statements.
3.
Government-issued ID.
4.
CPA letter confirming self-employment status (some lenders).
🔥
WATCH OUT!!!
The things that can undermine this strategy
● We will use only 1 year 1099 if we se a declining trend. Alert us so we can choose the proper lender.
● Converting from W-2 to 1099 mid-year. Disclose the transition clearly from the start — mid-process surprises cost everyone time. We have special programs for this... talk to us about how to make it work.
Your strategy starts here
Prepare your two most recent 1099s from all sources and two months of bank statements. We calculate income under both the 1099-only method and the bank statement method and show you which number is stronger.
🦸
Your Superpower
You built a client base that pays you on your terms. Independence was the whole point. Every 1099 is a relationship you earned — proof of work, proof of competence, proof of a business someone chose to hire.
🌀
What the Beige Box gets wrong
The Beige Box reads your earnings through the tax return, subtracts every legitimate write-off, and qualifies you on the taxable remainder. You earned $147,000. The 1099s prove it. The Beige Box removed every deduction your accountant was right to take and presented you with a qualifying income that looked nothing like what you actually made. It didn’t hate you. It just wasn’t designed for you.
The Strategy - how it works
The 1099-only path bypasses the tax return entirely. It reads your gross 1099 income and applies a standard expense factor instead of your actual deductions. The result is a qualifying income that, for most 1099 earners, is materially higher than the tax return shows.
What the Lender will look at
1.
One to two years of all 1099 forms from all sources.
2.
Two months of bank statements.
3.
Government-issued ID.
4.
CPA letter confirming self-employment status (some lenders).
🔥
WATCH OUT!!!
The things that can undermine this strategy
● We will use only 1 year 1099 if we se a declining trend. Alert us so we can choose the proper lender.
● Converting from W-2 to 1099 mid-year. Disclose the transition clearly from the start — mid-process surprises cost everyone time. We have special programs for this... talk to us about how to make it work.
Your strategy starts here
Prepare your two most recent 1099s from all sources and two months of bank statements. We calculate income under both the 1099-only method and the bank statement method and show you which number is stronger.