Bank statement loans
what you built... and what the system misses
Bank statement loans
what you built... and what the system misses
Bank statement loans
what you built... and what the system misses
You optimized your taxes perfectly.
The beige box penalized you for it. Here's the back door.
Bank statement loans read what actually came in — 12 or 24 months of deposits — instead of what survived the tax returns after every smart business decision you made.
Three lenders looked at the same tax return and said the same thing.
You’ve started to feel like the number on line 11 of the 1040 is a verdict.
It isn’t. It’s a tax strategy. Those are different things. The bank statements are the story. We just need to find the lender who’ll read them.
You optimized your taxes perfectly.
The beige box penalized you for it. Here's the back door.
Bank statement loans read what actually came in — 12 or 24 months of deposits — instead of what survived the Schedule C after every smart business decision you made.
Three lenders looked at the same tax return and said the same thing.
You’ve started to feel like the number on line 11 of the 1040 is a verdict.
It isn’t. It’s a tax strategy. Those are different things. The bank statements are the story. We just need to find the lender who’ll read them.
You optimized your taxes perfectly.
The beige box penalized you for it.
Here's the back door.
Bank statement loans read what actually came in — 12 or 24 months of deposits — instead of what survived the tax returns after every smart business decision you made.
Three lenders looked at the same tax return and said the same thing.
You’ve started to feel like the number on line 11 of the 1040 is a verdict.
It isn’t. It’s a tax strategy. Those are different things. The bank statements are the story. We just need to find the lender who’ll read them.
🦸
Your Superpower
You built a business and ran it the right way. Every write-off was a legitimate decision. The Beige Box reads those optimized return and mistakes your strategy for poverty. You are not broke. You are optimally deducted. Those are very different problems.
🌀
What the Beige Box gets wrong
Here’s the cruel joke of being self-employed: the better your accountant is, the worse your mortgage prospects look on paper. The Beige Box takes every write-off — every legitimate business decision — and subtracts it from what you’re allowed to borrow against. It penalizes intelligence. It mistakes strategy for struggle. It really sucks what it does to people who did everything right.
💥
The Strategy - how it works
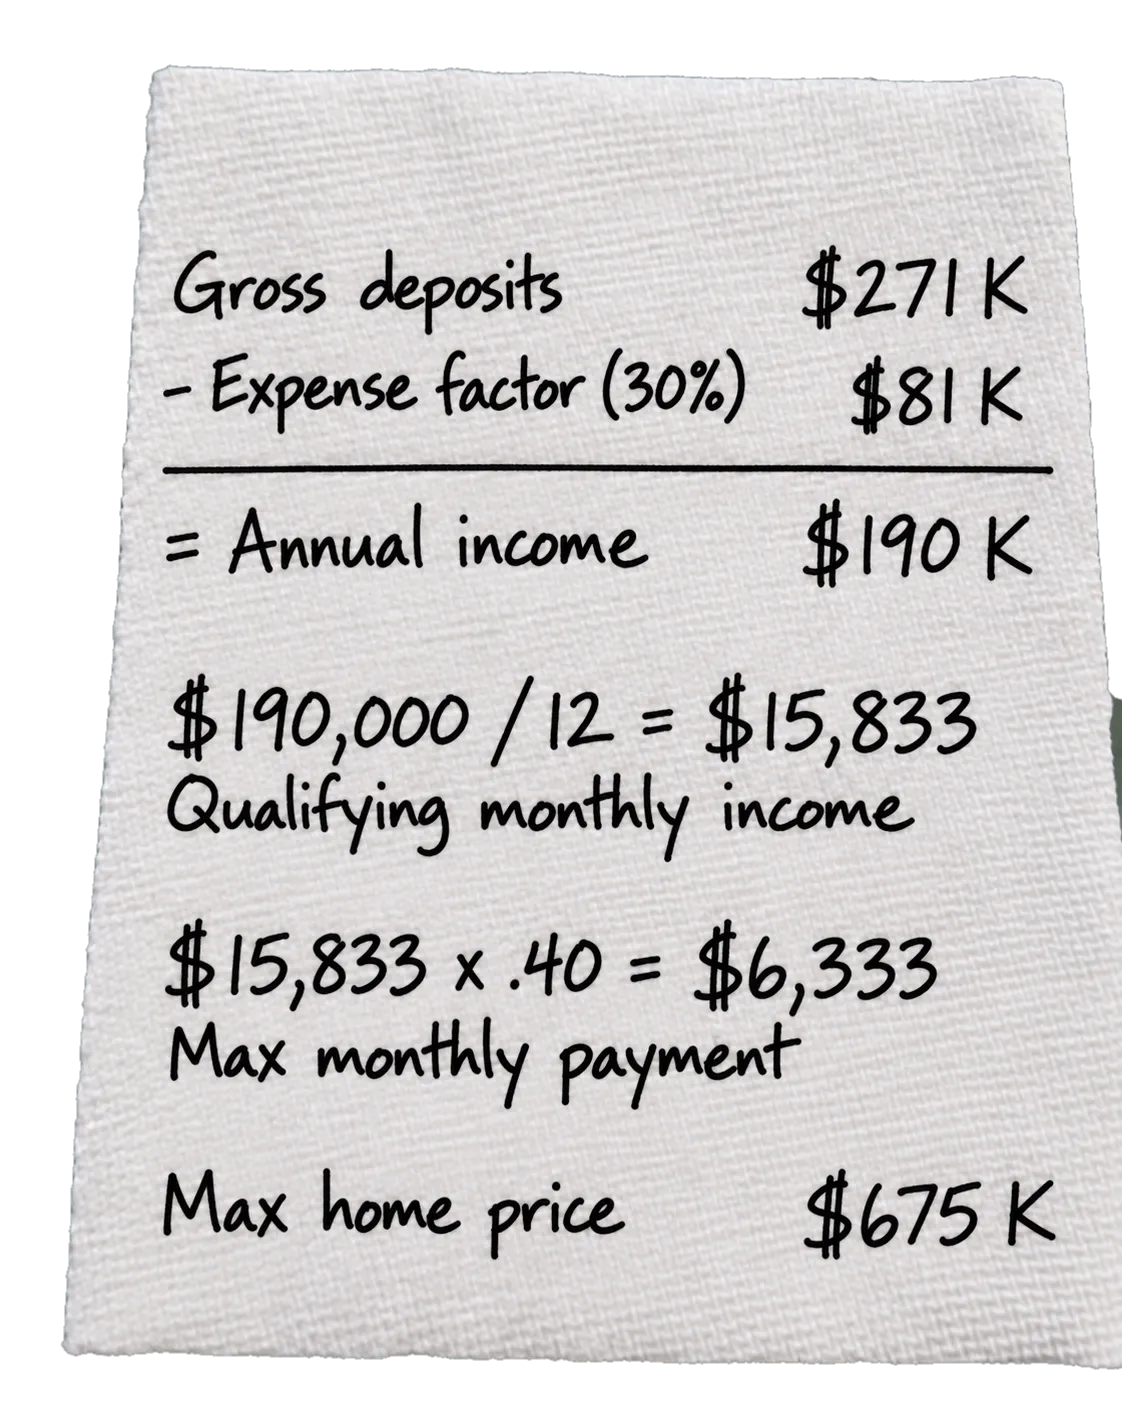
The bank statement method reads 12 or 24 consecutive months of actual deposits. For business accounts, lenders apply a standard expense factor — typically 30-50%. For most optimally deducted business owners, the deposit number is materially higher than the tax return.
What the Lender will look at
1.
12 or 24 consecutive months of bank statements — every page
2.
Business license or CPA letter confirming self-employment for 2+ years
3.
Government-issued ID
4.
12 months of personal bank statements or 2 months (If using business statements).
What underwriters are actually looking for
1.
Deposit consistency — erratic patterns invite questions
2.
No NSF or overdraft fees
3.
No large unexplained transfers
4.
Clear separation between business and personal funds
❌
not for everyone...
If your tax returns tell the real story of what you earn and conventional lending is available, it will almost certainly beat a bank statement loan on rate. This is built for the over-deducted borrower — the person whose tax optimization created a documentation mismatch with the standard system. We’ll tell you if that’s not your superpower.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● NSF or overdraft fees anywhere in the last 12 months. Even one flags the file. Clean the account history before applying — not during.
● Co-mingled deposits. Every transfer between personal and business accounts gets scrutinized. The cleaner the separation, the stronger the strategy.
● Large unexplained transfers right before applying. Underwriters have seen this a thousand times. Let the accounts be exactly what they are.
Your strategy starts here
Send your most recent tax return and two months of business bank statements. We run both numbers — tax return and bank statement — show you the comparison, and tell you which document makes the strongest case. No application. No credit pull.
🦸
Your Superpower
You built a business and ran it the right way. Every write-off was a legitimate decision. The Beige Box reads that optimized return and mistakes your strategy for poverty. You are not broke. You are over-deducted. Those are very different problems.
🌀
What the Beige Box gets wrong
Here’s the cruel joke of being self-employed: the better your accountant is, the worse your mortgage prospects look on paper. The Beige Box takes every write-off — every legitimate business decision — and subtracts it from what you’re allowed to borrow against. It penalizes intelligence. It mistakes strategy for struggle. It really sucks what it does to people who did everything right.
The Strategy - how it works
The bank statement method reads 12 or 24 consecutive months of actual deposits. For business accounts, lenders apply a standard expense factor — typically 50%. For most over-deducted business owners, the deposit number is materially higher than the tax return.
What the Lender will look at
1.
12 or 24 consecutive months of bank statements — every page
2.
Business license or CPA letter confirming self-employment for 2+ years
3.
Government-issued ID
4.
12 months of personal bank statements or 2 months (If using business statements).
What underwriters are actually looking for
1.
Deposit consistency — erratic patterns invite questions
2.
No NSF or overdraft fees
3.
No large unexplained transfers
4.
Clear separation between business and personal funds
❌
not for everyone...
If your tax returns tell the real story of what you earn and conventional lending is available, it will almost certainly beat a bank statement loan on rate. This is built for the over-deducted borrower — the person whose tax optimization created a documentation mismatch with the standard system. We’ll tell you if that’s not your superpower.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● NSF or overdraft fees anywhere in the last 12 months. Even one flags the file. Clean the account history before applying — not during.
● Co-mingled deposits. Every transfer between personal and business accounts gets scrutinized. The cleaner the separation, the stronger the strategy.
● Large unexplained transfers right before applying. Underwriters have seen this a thousand times. Let the accounts be exactly what they are.
Your strategy starts here
Send your most recent tax return and two months of business bank statements. We run both numbers — tax return and bank statement — show you the comparison, and tell you which document makes the strongest case. No application. No credit pull.
🦸
Your Superpower
You built a business and ran it the right way. Every write-off was a legitimate decision. The Beige Box reads those optimized return and mistakes your strategy for poverty. You are not broke. You are optimally deducted. Those are very different problems.
🌀
What the Beige Box gets wrong
Here’s the cruel joke of being self-employed: the better your accountant is, the worse your mortgage prospects look on paper. The Beige Box takes every write-off — every legitimate business decision — and subtracts it from what you’re allowed to borrow against. It penalizes intelligence. It mistakes strategy for struggle. It really sucks what it does to people who did everything right.
The Strategy - how it works
The bank statement method reads 12 or 24 consecutive months of actual deposits. For business accounts, lenders apply a standard expense factor — typically 30-50%. For most optimally deducted business owners, the deposit number is materially higher than the tax return.
What the Lender will look at
1.
12 or 24 consecutive months of bank statements — every page
2.
Business license or CPA letter confirming self-employment for 2+ years
3.
Government-issued ID
4.
12 months of personal bank statements or 2 months (If using business statements).
What underwriters are actually looking for
1.
Deposit consistency — erratic patterns invite questions
2.
No NSF or overdraft fees
3.
No large unexplained transfers
4.
Clear separation between business and personal funds
❌
not for everyone...
If your tax returns tell the real story of what you earn and conventional lending is available, it will almost certainly beat a bank statement loan on rate. This is built for the over-deducted borrower — the person whose tax optimization created a documentation mismatch with the standard system. We’ll tell you if that’s not your superpower.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● NSF or overdraft fees anywhere in the last 12 months. Even one flags the file. Clean the account history before applying — not during.
● Co-mingled deposits. Every transfer between personal and business accounts gets scrutinized. The cleaner the separation, the stronger the strategy.
● Large unexplained transfers right before applying. Underwriters have seen this a thousand times. Let the accounts be exactly what they are.
Your strategy starts here
Send your most recent tax return and two months of business bank statements. We run both numbers — tax return and bank statement — show you the comparison, and tell you which document makes the strongest case. No application. No credit pull.