Asset qualifier plus
what you built... and what the system misses
Asset qualifier plus
what you built... and what the system misses
Asset qualifier plus
what you built... and what the system misses
You built the Wealth.
the beige box wants a w-2 you don't have.
Asset Qualifier Plus — also known as asset depletion and asset utilization — converts documented liquid assets into qualifying mortgage income using a formula lenders accept.
Every lender asks for the same thing: a W-2.
Maybe you just ditched your w-2 gig...
maybe you haven't had one in years...
maybe you never had one.
You have accounts the size of most people’s retirement. You have a financial advisor. You have real, documented, liquid wealth.
And the Beige Box still asked for a pay stub.
🦸
Your Superpower
You spent decades building something real — retirement accounts, investment portfolios, a business you sold at exactly the right time, a career that produced assets instead of a salary. The mortgage system was built for people who trade time for a paycheck every two weeks. It has no good answer for the person who built something better.
🌀
What the Beige Box gets wrong
The Beige Box requires recurring monthly employment income. For a buyer sitting on $3 million in a brokerage account, this demand is a category error. The wealth exists. It is liquid. It earns. The system just cannot see it. It really sucks what it does to people who did everything right and then showed up with more money than the loan officer earns in a decade and got told they don’t qualify.
💥
The Strategy - how it works
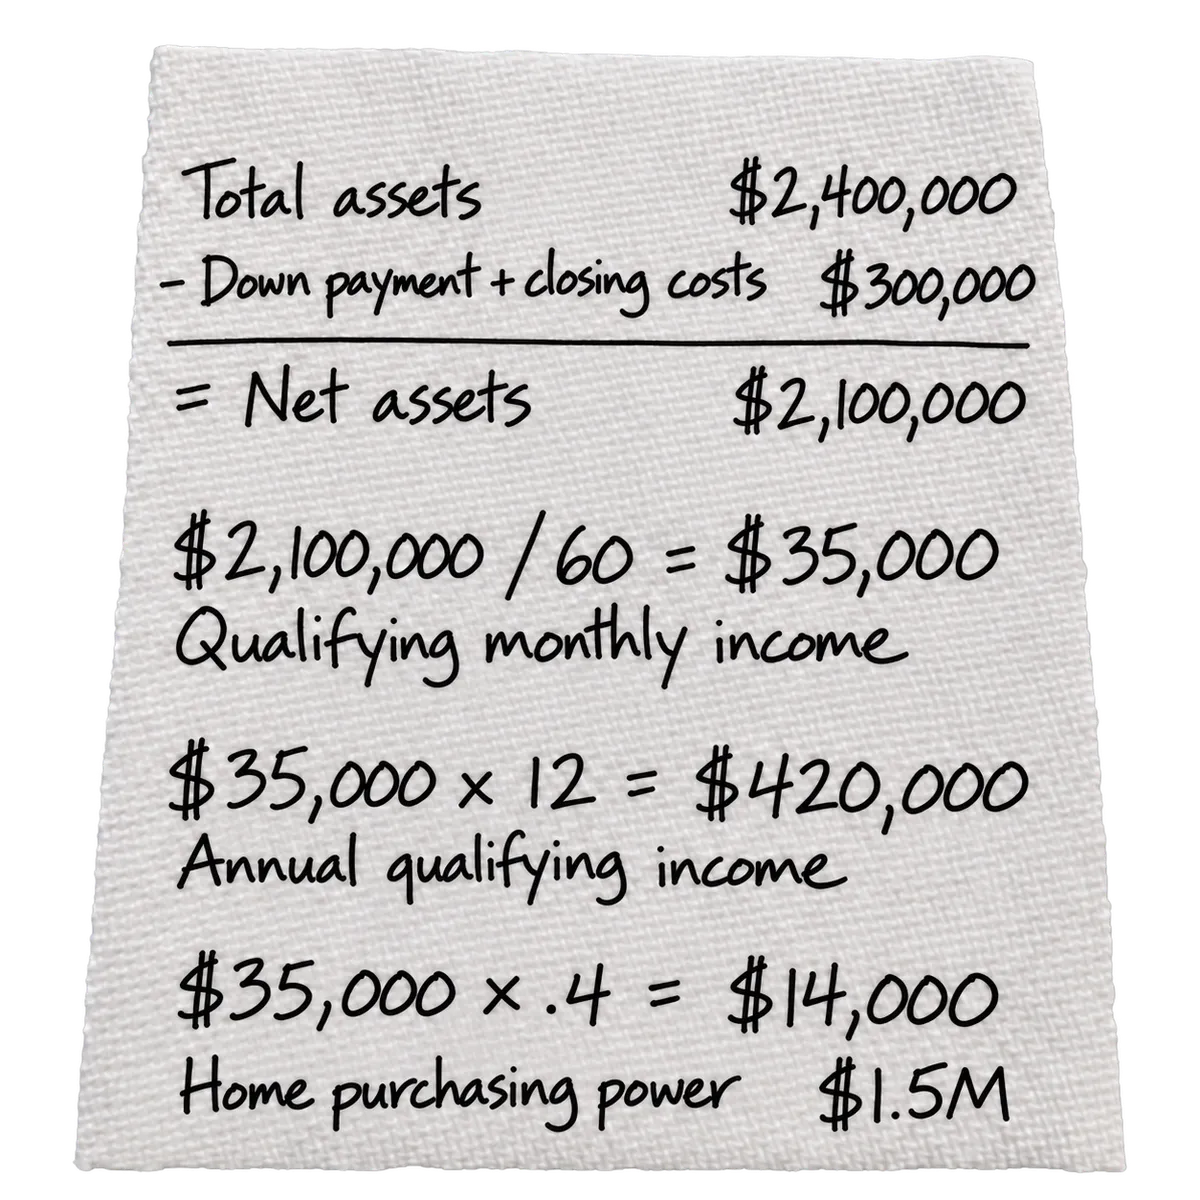
Asset Qualifier Plus converts the documented liquid asset balance into an imputed qualifying monthly income. This is not money being spent. It is a documented calculation — eligible assets divided by the loan term in months — that satisfies the underwriter’s income requirement without requiring a paycheck that no longer exists. You don't even need to start drawing on those assets.
Asset type
HOW IT COUNTS IN THE STRATEGY TOWARDS INCOME
Checking and savings
100% eligible /60
Money market accounts
100% eligible /60
Brokerage / investment accounts
100% eligible /60
IRA / SEP
90-100% eligible /36
Business accounts
Lender-specific — requires documentation of accessibility
Crypto and non-traditional assets
Varies by lender — must typically be converted and seasoned first
varies by lender. Not a commitment to lend.
What the Lender will look at
1.
Three to four months of statements for every asset account being used.
2.
Verification of account ownership and accessibility.
3.
Government-issued ID.
4.
Documentation of any recent large deposits or transfers.
Who this strategy is Built for
1.
Retired buyers with substantial liquid assets and no recurring paycheck.
2.
Business sellers with a recent liquidity event.
3.
High-net-worth borrowers whose wealth sits in portfolios, not payroll.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Moving money between accounts in the 60 days before applying. Underwriters look at where every dollar came from. Transfers create sourcing questions. Let accounts sit where they are.
● Large deposits in the 60-day window. Any significant deposit requires documentation. Unexplained money is a problem even when it’s yours.
● Accounts held jointly with someone not on the loan. Lenders may only count your percentage — or require additional documentation of your access to the full balance.
Your strategy starts here
Describe what you have — what types of accounts, approximate total balances, and how long the money has been there. We run the Asset Qualifier Plus calculation before you send a single statement and tell you whether the formula produces enough qualifying income for the purchase you’re targeting. No application. No credit pull.
🦸
Your Superpower
You spent decades building something real — retirement accounts, investment portfolios, a business you sold at exactly the right time, a career that produced assets instead of a salary. The mortgage system was built for people who trade time for a paycheck every two weeks. It has no good answer for the person who built something better.
🌀
What the Beige Box gets wrong
The Beige Box requires recurring monthly employment income. For a buyer sitting on $3 million in a brokerage account, this demand is a category error. The wealth exists. It is liquid. It earns. The system just cannot see it. It really sucks what it does to people who did everything right and then showed up with more money than the loan officer earns in a decade and got told they don’t qualify.
The Strategy - how it works
Asset Qualifier Plus converts the documented liquid asset balance into an imputed qualifying monthly income. This is not money being spent. It is a documented calculation — eligible assets divided by the loan term in months — that satisfies the underwriter’s income requirement without requiring a paycheck that no longer exists. You don't even need to start drawing on those assets.
Asset type
HOW IT COUNTS IN THE STRATEGY TOWARDS INCOME
Checking and savingsS-corp
100% eligible /60
Money market accounts
100% eligible /60
Brokerage / investment accounts
100% eligible /60
IRA / SEP
90-100% eligible /36
Business accounts
Lender-specific — requires documentation of accessibility
Crypto and non-traditional assets
Varies by lender — must typically be converted and seasoned first
varies by lender. Not a commitment to lend.
What the Lender will look at
1.
Three to four months of statements for every asset account being used.
2.
Verification of account ownership and accessibility.
3.
Government-issued ID.
4.
Documentation of any recent large deposits or transfers.
What underwriters are actually looking for
1.
Retired buyers with substantial liquid assets and no recurring paycheck.
2.
Business sellers with a recent liquidity event.
3.
High-net-worth borrowers whose wealth sits in portfolios, not payroll.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Moving money between accounts in the 60 days before applying. Underwriters look at where every dollar came from. Transfers create sourcing questions. Let accounts sit where they are.
● Large deposits in the 60-day window. Any significant deposit requires documentation. Unexplained money is a problem even when it’s yours.
● Accounts held jointly with someone not on the loan. Lenders may only count your percentage — or require additional documentation of your access to the full balance.
Your strategy starts here
Describe what you have — what types of accounts, approximate total balances, and how long the money has been there. We run the Asset Qualifier Plus calculation before you send a single statement and tell you whether the formula produces enough qualifying income for the purchase you’re targeting. No application. No credit pull.
🦸
Your Superpower
You spent decades building something real — retirement accounts, investment portfolios, a business you sold at exactly the right time, a career that produced assets instead of a salary. The mortgage system was built for people who trade time for a paycheck every two weeks. It has no good answer for the person who built something better.
🌀
What the Beige Box gets wrong
The Beige Box requires recurring monthly employment income. For a buyer sitting on $3 million in a brokerage account, this demand is a category error. The wealth exists. It is liquid. It earns. The system just cannot see it. It really sucks what it does to people who did everything right and then showed up with more money than the loan officer earns in a decade and got told they don’t qualify.
The Strategy - how it works
Asset Qualifier Plus converts the documented liquid asset balance into an imputed qualifying monthly income. This is not money being spent. It is a documented calculation — eligible assets divided by the loan term in months — that satisfies the underwriter’s income requirement without requiring a paycheck that no longer exists. You don't even need to start drawing on those assets.
Asset type
HOW IT COUNTS IN THE STRATEGY TOWARDS INCOME
Checking and savingsS-corp
100% eligible /60
Money market accounts
100% eligible /60
Brokerage / investment accounts
100% eligible /60
IRA /SEP
90-100% eligible /36
Business accounts
Lender-specific — requires documentation of accessibility
Crypto and non-traditional assets
Varies by lender — must typically be converted and seasoned first
varies by lender. Not a commitment to lend.
What the Lender will look at
1.
Three to four months of statements for every asset account being used.
2.
Verification of account ownership and accessibility.
3.
Government-issued ID.
4.
Documentation of any recent large deposits or transfers.
Who this strategy is Built for
1.
Retired buyers with substantial liquid assets and no recurring paycheck.
2.
Business sellers with a recent liquidity event.
3.
High-net-worth borrowers whose wealth sits in portfolios, not payroll.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Moving money between accounts in the 60 days before applying. Underwriters look at where every dollar came from. Transfers create sourcing questions. Let accounts sit where they are.
● Large deposits in the 60-day window. Any significant deposit requires documentation. Unexplained money is a problem even when it’s yours.
● Accounts held jointly with someone not on the loan. Lenders may only count your percentage — or require additional documentation of your access to the full balance.
Your strategy starts here
Describe what you have — what types of accounts, approximate total balances, and how long the money has been there. We run the Asset Qualifier Plus calculation before you send a single statement and tell you whether the formula produces enough qualifying income for the purchase you’re targeting. No application. No credit pull.