DSCR LOANS
what you built... and what the system misses
DSCR LOANS
what you built... and what the system misses
DSCR LOANS
what you built... and what the system misses
Your portfolio is growing
your lender is sweating. good.
DSCR lending qualifies the property on its own rental income — not your personal debt-to-income ratio.
"Your DTI is too high."
"We can’t use projected rental income."
"You’ve reached your conventional loan limit."
You’ve heard one of these. Maybe all three. And every time, what you wanted to say was: cool. What else you got.
Your portfolio is growing
The lender is sweating. good.
DSCR lending qualifies the property on its own rental income — not your personal debt-to-income ratio.
"Your DTI is too high."
"We can’t use projected rental income."
"You’ve reached your conventional loan limit."
You’ve heard one of these. Maybe all three. And every time, what you wanted to say was: cool. What else you got.
Your portfolio is growing
The beige box penalized you for it.
Here's the back door.
DSCR lending qualifies the property on its own rental income — not your personal debt-to-income ratio.
"Your DTI is too high."
"We can’t use projected rental income."
"You’ve reached your conventional loan limit."
You’ve heard one of these. Maybe all three. And every time, what you wanted to say was: cool. What else you got.
🦸
Your Superpower
Every property you acquired is a home someone actually lives in. You think in cap rates. You run the numbers before you make an offer. The Beige Box doesn’t hate investors — it doesn’t know you exist. It only knows the shape of the form.
🌀
What the Beige Box gets wrong
Every conventional mortgage you take as an investor adds to your personal DTI. The portfolio grows, the ratio climbs, and at some point the Beige Box says stop — even when every property cash-flows and the new deal absolutely pencils. It is not evaluating your portfolio. It is filling out a form.
💥
The Strategy - how it works
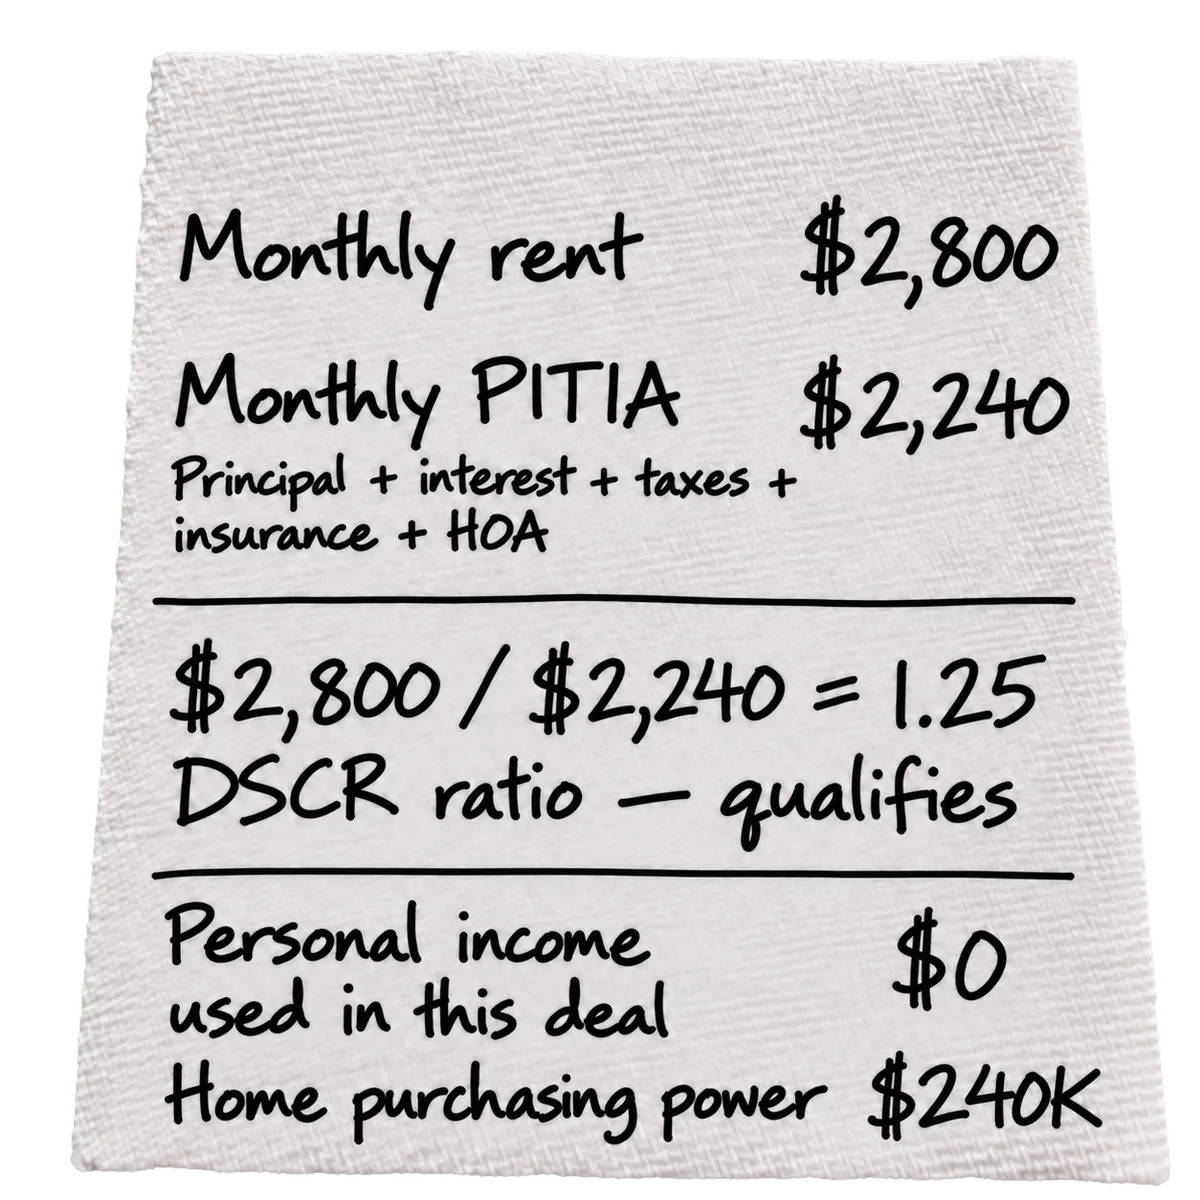
DSCR lending removes your personal income from the equation entirely. The lender asks one question: does the gross monthly rent cover the monthly PITIA? If the ratio is 1.0 or above (sometimes we can even go as low as .55), the property qualifies. Your W-2, your self-employment income, your nine other mortgages — none of it enters the calculation for this deal.
What the Lender will look at
1.
Signed lease or market rent estimate.
2.
Property appraisal.
3.
Credit score — typically 660+ minimum, better pricing above 700.
4.
Reserves — typically 3–6 months of PITIA in liquid accounts after closing.
5.
Entity documentation if closing in an LLC.
who this strategy is built for
1.
Investors who have acquired multiple properties over conventional limits.
2.
Buyers purchasing in an LLC or other entity from day one.
3.
Investors who want the deal evaluated on the property, not their personal finances.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Short-term rental property DSCR loans have their own unique guidelines. Confirm the lender’s STR policy before you make any offer on a platform property.
● Transferring the deed to an LLC after closing on a personal loan can trigger the due-on-sale clause. Close in the LLC from day one — not after.
● Reserves. Budget 3–6 months of PITIA in liquid accounts after closing — a hard requirement on most DSCR products.
Your strategy starts here
Send the property address and the current or estimated market rent. We pull property tax bills, model the real PITIA, calculate the DSCR, and tell you whether this deal belongs in your portfolio — before you write the offer.
🦸
Your Superpower
Every property you acquired is a home someone actually lives in. You think in cap rates. You run the numbers before you make an offer. The Beige Box doesn’t hate investors — it doesn’t know you exist. It only knows the shape of the form.
🌀
What the Beige Box gets wrong
Every conventional mortgage you take as an investor adds to your personal DTI. The portfolio grows, the ratio climbs, and at some point the Beige Box says stop — even when every property cash-flows and the new deal absolutely pencils. It is not evaluating your portfolio. It is filling out a form.
The Strategy - how it works
DSCR lending removes your personal income from the equation entirely. The lender asks one question: does the gross monthly rent cover the monthly PITIA? If the ratio is 1.0 or above (sometimes we can even go as low as .55), the property qualifies. Your W-2, your self-employment income, your nine other mortgages — none of it enters the calculation for this deal.
What the Lender will look at
1.
Signed lease or market rent estimate.
2.
Property appraisal.
3.
Credit score — typically 660+ minimum, better pricing above 700.
4.
Reserves — typically 3–6 months of PITIA in liquid accounts after closing.
5.
Entity documentation if closing in an LLC.
who this strategy is built for
1.
Investors who have acquired multiple properties over conventional limits.
2.
Buyers purchasing in an LLC or other entity from day one.
3.
Investors who want the deal evaluated on the property, not their personal finances.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Short-term rental property DSCR loans have their own unique guidelines. Confirm the lender’s STR policy before you make any offer on a platform property.
● Transferring the deed to an LLC after closing on a personal loan can trigger the due-on-sale clause. Close in the LLC from day one — not after.
● Reserves. Budget 3–6 months of PITIA in liquid accounts after closing — a hard requirement on most DSCR products.
Your strategy starts here
Send the property address and the current or estimated market rent. We pull Harris County Appraisal District data, model the real PITIA, calculate the DSCR, and tell you whether this deal belongs in your portfolio — before you write the offer.
🦸
Your Superpower
Every property you acquired is a home someone actually lives in. You think in cap rates. You run the numbers before you make an offer. The Beige Box doesn’t hate investors — it doesn’t know you exist. It only knows the shape of the form.
🌀
What the Beige Box gets wrong
Every conventional mortgage you take as an investor adds to your personal DTI. The portfolio grows, the ratio climbs, and at some point the Beige Box says stop — even when every property cash-flows and the new deal absolutely pencils. It is not evaluating your portfolio. It is filling out a form.
The Strategy - how it works
DSCR lending removes your personal income from the equation entirely. The lender asks one question: does the gross monthly rent cover the monthly PITIA? If the ratio is 1.0 or above (sometimes we can even go as low as .55), the property qualifies. Your W-2, your self-employment income, your nine other mortgages — none of it enters the calculation for this deal.
What the Lender will look at
1.
Signed lease or market rent estimate.
2.
Property appraisal.
3.
Credit score — typically 660+ minimum, better pricing above 700.
4.
Reserves — typically 3–6 months of PITIA in liquid accounts after closing.
5.
Entity documentation if closing in an LLC.
who this strategy is built for
1.
Investors who have acquired multiple properties over conventional limits.
2.
Buyers purchasing in an LLC or other entity from day one.
3.
Investors who want the deal evaluated on the property, not their personal finances.
🔥
WATCH OUT!!!
The things that can undermine this strategy
● Short-term rental property DSCR loans have their own unique guidelines. Confirm the lender’s STR policy before you make any offer on a platform property.
● Transferring the deed to an LLC after closing on a personal loan can trigger the due-on-sale clause. Close in the LLC from day one — not after.
● Reserves. Budget 3–6 months of PITIA in liquid accounts after closing — a hard requirement on most DSCR products.
Your strategy starts here
Send the property address and the current or estimated market rent. We pull property tax bills, model the real PITIA, calculate the DSCR, and tell you whether this deal belongs in your portfolio — before you write the offer.